
Social Security Disability Offsets
Earnings from Substantial Employment
Many people think you cannot work at all when you receive Social Security Disability (SSD) benefits or you will lose your benefits. This is not true, although there are limits on how much you can earn before it affects your benefits. In most cases, your Medicare benefits will continue and you are also allowed to deduct certain work expenses from the gross income for purposes of calculating your earnings. If you are going to make an effort to work, you should review the Social Security Administration (SSA) rules very carefully. Also, before you make that effort, to see if you are able, you might want to volunteer somewhere for a short time and see if you can handle the consistent effort required.
Trial Work Period
The SSA allows you a trial work period followed by an extended eligibility work period. If you can work 9 months (they do not need to be consecutive) within a 60 month period, the trial work period ends, followed by the extended period of eligibility. There will be no loss of benefits no matter how much you make during the trial work period months. The minimum amount of money to establish a trial work month is $720 in 2010. This amount increases each year, and the specific rules vary for employees, self-employed and blind persons. Although the monthly amount of money you make during the trial work period does not matter, during the extended period of eligiblity which follows, a key factor is the amount of money you make.
Extended period of eligibility
After your trial work period, you have 36 months during which you can work and still receive benefits for any month your earnings are not deemed “substantial.” In 2010, earnings of $1000 or more ($1,640 if you are blind) are considered substantial. This amount also increases each year. The SSA will deduct work expenses from the gross amount of your earnings. No new application or disability decision is needed for you to receive a Social Security disability benefit during this period.
Workers Compensation Benefits
You can receive both Workers Compensation(WC) and SSD benefits but you cannot receive a combined benefit of more than 80% of your average current earnings as calculated by the SSA. The SSA will take the offset from your SSD benefits. If your WC stops, your SSD will usually increase.
Unemployment Compensation
The interplay between Unemployment Compensation (UC) and SSD is a complex one. People often ask if they can receive both. The general rule is that the SSA will take an offset on retroactive benefit awards for any UC you might have received while your SSD claim is pending. Although one can be available for UC purposes for work within their limitations, in a claim for SSD one is alleging that they are unable to engage in substantial gainful employment.
Long Term Disability Insurance
Although there is no offset to your SSD if you receive Long Term Disability benefits, the LTD carrier might take an offset for receipt of SSD. This varies, so you need to check with your LTD carrier and LTD contract to find out how it might affect you.
For official information on this subject go to these links:
http://www.ssa.gov/pubs/10095.html
http://www.ssa.gov/pubs/10029.html
http://www.ssa.gov/work/
Monday, August 23, 2010


Tuesday, July 13, 2010
PA AUTO INSURANCE: MAKING THE PROPERTY DAMAGE CLAIM

HOW DOES IT WORK?
Pennsylvania requires at least $5,000 of property damage coverage on your auto insurance policy for property damage to another driver’s vehicle for an accident in which you are at fault. You can elect to maintain a higher amount of coverage
Property Damage Coverage:
Property damage is only available against the other driver’s policy and is based upon fault. In other words, you do not have property damage for yourself on your own policy; it is only there to reimburse someone else if you cause damage, much like liability limits for personal injuries. If someone causes you damage, you would make a claim against their property damage coverage, not against your own, as your own is not available to you as a first party benefit. (You can have collision coverage and make a claim against that coverage, which is discussed below.) The claim can be made for the fair market value of the vehicle up to the maximum of the coverage chosen by the insured driver.
Collision and Comprehensive Coverage:
These optional coverages offer you additional protection against different damage. Collision coverage applies to damage caused by an auto accident, minus your deductible. Comprehensive coverage applies to damage caused by other incidents such as theft or falling branches, minus a deductible.
MAKING THE CLAIM
If your car has been damaged in an auto accident caused by another driver, the easiest approach is to make the claim directly against their auto policy if the insurance company is accepting 100% liability. Then it is just a matter of negotiating the fair market value of the vehicle.
If, on the other hand, there is a disagreement over liability, sometimes it is best to make the claim against your own policy, IF you have collision coverage. Then your company pays you for the damge, minus your deductible. What then happens is that your insurance company makes a claim against the policy of the other driver which is resolved by way of an intercompany arbitration, where it is decided what percentage of negligence on the part of each driver caused the accident. If you were 0% liabile then you would get the deductible returned to you at that time. If it is found that you were partly at fault, your insurance company does have the right to refund your deductible at a prorated amount.
The “made whole” doctrine “requires that an insured recover the full amount of his losses before his insurer may demand reimbursement for any payments previously made to the insured under an insurance policy.” Harnick, 2009 U.S. Dist. LEXIS 43126 at *9. Jones v. Nationwide , 2010 PA Super 90 (2008) http://www.pacourts.us/OpPosting/Superior/out/a05017_10.pdf
Property damage is usually resolved without litigation, even where there are personal injuries for which a claim is later made by way of a lawsuit. Additional damages such as rental car expenses and towing/storage costs are covered immediately if the other driver has this coverage or under your own policy.
MEASURING PROPERTY DAMAGE
In PA, the general rule is that the insurance carrier or the defendant need only pay the cost of repair or the cost of replacement value on the vehicle, whichever is less. It is general wisdom that when the repair cost exceeds 80% of the value of the car, it will be totaled. The most common method to value the car is the “blue book” and other online resources below:
Kelley Blue Book http://www.kbb.com/
http://www.redbook.com/
http://www.vehix.com/
http://www.edmunds.com/
http://www.nada.com/
Sometimes you can keep the totaled vehicle by agreement with the adjuster. They may want to pay less, which represents the fair salvage value of the car. However, you may want the car because you know someone who can repair it for use.Some states require a certificate to show that a vehicle has been previously totaled.
People are often confronted with the situation that they still owe more on the car loan than what is being paid out as the fair market value of the car. The best way to insure against this is to purchase gap coverage when you buy the car. Gap coverage would pay the difference between the outstanding balance on the loan and the fair market value at the time of accident.
Once the damage on a vehicle has been assessed and a market value has been established, the PIP carrier will want to settle quickly to cut their costs for storage of the vehicle.

The standard policy will be a set amount of money per day for "up to 30 days of use." Once a settlement has been reached for property damage, the rule of thumb is to allow use of a rental car for 3 to 4 days after settlement. This is a bit flexible and may depend on the individual adjuster and circumstances. However, the fact that a policy states that a rental car will be covered for up to 30 days does not mean that the full 30 days will always be allowed.
CAR IS REPAIRED:
The defendant is responsible for reasonable rental while Plaintiff has the damaged vehicle repaired. Sometimes, you can negotiate payment for rental up front with the adjuster. Sometimes, they will attempt to limit the time period. If you cannot get full coverage, you may have to cover the cost yourself and claim as damages later the amount you had to put out for rental. If you have your own rental provision in your first party coverage, it may be better to use that and then let your carrier go to the defendant for subrogation.
Monday, May 24, 2010
Who Let the Dogs Out?

Pennsylvania, like all states, has a time limit in which to file a personal injury action. Different rules apply to different situations, so it is best to obtain legal represenation immediately to make sure you are covered and do not miss the deadlines.
You should act now to speak to an attorney who can help you. When a dog bite occurs, records must be obtained, photos must be taken and the appropriate claims must be reported to the insurance companies involved. The longer you wait, the harder it is to take control of the situation.
The claim for damages is handled by the homeowners’ insurance policy maintained by the dog owner. Close to one third of claims against homeowners’ policies are for dog bite attacks. The dog owner is responsible for the behavior of the dog. There is no need to worry if the owner is a neighbor or a friend...the insurance company handles the matter for them. This is why we all have homeowners’ policies and this is why we pay our premiums.
The damages involved can include the medical expenses, current and future, lost wages, pain and suffering, disfigurement and scarring and emotional damages. The emotional damages from a dog bite can be devastating. Most scars require at least a year for a doctor to determine the course of treatment and whether the scar is permanent and requires plasctic surgery.
Children are subject to dog bites and are particularly vulnerable to bites around the head and face. They simply do not know how to protect themselves. The emotional trauma to them will last a lifetime. Treatment for a child may have to wait even longer than a year.
Pennsylvania has a hybrid approach to liability. There is strict liability for all damages incurred if the dog previously exhibited dangerous behavior or if the injuries are severe. There is also strict liability for medical bills. Other circumstances giving rise to laiblity occur where the owner was negligent or violated the animal control law, which requires that owners keep their dogs under control, either confined at home, or on a leash when away from the home.
Important Steps to Take After a Dog Bite
- Seek immediate medical attention — even if it seems like a minor bite-this is especially important if the dog is not current on shots.
- Take photographs of all injuries, even before there is cleanup of the wounds, and after cleanup of the wounds. See this page for instruction on taking photos: http://www.jjsassoc.net/Preserving_Evidencel.htm
- Gather information from witnesses, if there were any. Get names, addresses, and phone numbers.
- Report the matter immediately to the police. This creates a record of the incident.
- Obtain the dog's veterinarian records about shots, diseases and other medical history.
- Do not try to negotiate with the animal's owner privately. Make sure that the claim is directed to their homeowner’s insurer. It is best not to engage in conversations about this matter with the owner.
- Talk to an experienced personal injury attorney as soon as possible.
SOME USEFUL LINKS:
http://www.puppiesndogs.com/dogbiteprevention.php
http://www.dogbitelaw.com/PAGES/Pennsylvania.html
http://www.pacode.com/secure/data/007/chapter27.html
http://www.dogbitelaw.com/
http://www.dogexpert.com/
http://www.doggonesafe.com/
http://www.dogsbite.org/
Call me at 215.752-3732 or visit me at
http://www.jjsassoc.net
Monday, May 3, 2010
Cruising Out of Control
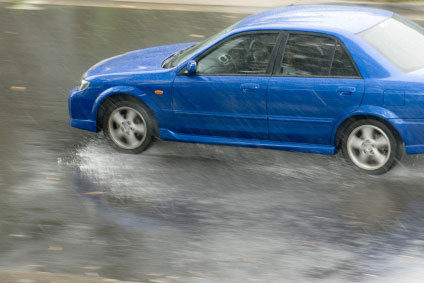
A 36 year old female had an accident in which she totaled her car. It was raining, though not excessively, when her car suddenly began to hydro-plane and literally flew through the air. She was not seriously injured but very stunned at the sudden occurrence! When she explained to the highway patrolman what had happened he told her something that every driver should know:
NEVER DRIVE IN THE RAIN WITH YOUR CRUISE CONTROL ON!!!
She thought she was being cautious by setting the cruise control and maintaining a safe consistent speed in the rain. But the highway patrolman told her that if the cruise control is on when your car begins to hydro-plane and your tires lose contact with the pavement, your car will accelerate to a higher rate of speed making you take off like an airplane. She told the patrolman that was exactly what had occurred. The patrolman said this warning should be listed on the driver's seat sun-visor:
NEVER USE THE CRUISE CONTROL WHEN THE PAVEMENT IS WET OR ICY
We tell our teenagers to set the cruise control and drive a safe speed, but we don't tell them to use the cruise control only when the pavement is dry.
MY THOUGHTS: When I took the time to do some online research, I discovered that the Insurance Corporation of British Columbia advises motorists to turn off the cruise control in dark and wet conditions. The fact of the matter is that driving in the rain or snow or wet conditions already creates some hazard and risk of hydro-planing. The driver must be able to react quickly. Although the cruise control disengages rather quickly, it is still an extra step in regaining control. Until the cruise control is disengaged, the vehicle continues moving at the set speed. Immediate reduction of speed is critical.
The cruise control cannot anticipate changes in the road surface or the direction of the road, either of which can alert a watchful driver to slow down in anticipation of the big puddle ahead or the sharp curve in the road. Another consideration is the fact that when you have the cruise control on, you tend to cruise, literally...and many of us move our foot a little bit away from the brake pedal to give it a rest. All of these factors can lead to disaster if you begin to hydro-plane.
http://www.icbc.com/about%20ICBC/news_room/2009news_releases/nov_09#5p
You can find anything online, which includes all sorts of sites dedicated to debunking hoaxes and scams. The email story above has been around for awhile and got around enough to be the subject of blog posts like the one in the link below. While the author attempts to debunk the story as to cruise control causing hydro-planing, he does admit that it is better not to use cruise control in rainy and wet road conditions. If you want to examine the whys and wherefores, there is a link in the article which explains the issues in more depth. http://www.hoax-slayer.com/cruise-control-warning.html
MY CONCLUSION: I will not engage the cruise control when I am traveling in rainy or wet conditions. In rainy conditions, the wheels of the car can spin along the surface of the water on the road. Also, the wetness can bring the oil embedded in the blacktop from exhaust fumes to the top of the road as well, making for more slippery conditions and catastrophic car accidents. Cruise control can just make you lose control!
Do you have questions? You can find me at www.jjsassoc.net
Photo from http://www.hoax-slayer.com/cruise-control-warning.html
Wednesday, April 21, 2010
Is Age Just A Number?
This is a good article. I have found much of what is written here to be true in my 29 years of practice in personal injury cases as well. There are no easy answers. For the young driver, they pass their test and then they are let loose. Parents can only try their best to instill good judgment into their sons and daughters. Having two young sons, I wish the legal age to drive in PA is raised to 18!
For the older driver, I really do think that states should require some sort of retesting at a certain age. While I know I would not appreciate it some day if it is applied to me because I have reached a certain age, the fact is that there are people out there driving who should not be behind the wheel because their ability to drive has been affected.
POSTED AT COLLISIONMAX ON MERCHANTCIRLE.COM
http://www.merchantcircle.com/business/CollisionMax.of.Oxford.Valley.215-943-9600
“Automobile accidents are the leading cause of death and injury in all age groups. Statistics show that 40,000 of the nearly 6 million accidents each year result in fatalities. Alcohol is a factor in 40 per cent of these fatalities and speeding accounts for 29 percent of deaths. Speeding and alcohol are not the only problems we face on the road —young drivers (16-20 years of age) and older drivers (over the age of 69) have much higher fatality rates than those between the ages of 21 and 69.
Teen drivers are more likely to be the cause of their own accidents than more seasoned motorists because they lack maturity and driving experience. Immaturity is evident in such risky practices as tailgating and speeding. Jim Tornetta, president of 1. CollisionMax, says, "Many teens are ill-equipped to handle emergency driving maneuvers, and the majority of teen injuries and fatalities come about in single-vehicle crashes." He continues, "They simply lose control of the car and cannot recover in time." Alcohol, cell phones, loud music and distractions from other teenage passengers are also significant contributing factors to teen crashes.
Although they typically wear their seat belts, drive the speed limit, and rarely take risks on the road, senior citizens' crash rates have skyrocketed. Highway deaths for motorists under 65 have dropped 3 percent since 1995, to 33,659 last year. Among seniors, however, deaths jumped 15 percent over the same period, to 8,141 last year. During the past two decades, the fatality rate of senior drivers has also risen.
The National Highway Traffic Safety Administration estimates that fatalities among elderly drivers will increase faster than their population, to more than 23,000 annually - 63 deaths a day - by 2030. Although they don't drive as recklessly as some younger motorists, seniors have difficulty with reaction times, reading road signs and judging distances.
States are struggling for an answer to senior driving issues. Florida is enlarging some highway street signs from 12 inches to 36 to accommodate the weaker vision of its 2.9 million elderly drivers. Nine states are considering legislation that requires doctors to report serious medical conditions afflicting seniors to motor-vehicle authorities. Officials could then order new driving tests or revoke licenses.
Although there is no easy answer, government agencies are introducing new programs to help teens and seniors become better drivers. With a little work, the roads will be safer for motorists of all ages.”
Wednesday, April 7, 2010
Wednesday, March 31, 2010
The Tax Man Cometh

If there is money coming into the house, the tax man will find a way to come and get it!!! I have outlined a few situations below which affect clients who receive certain monetary benefits as a result of legal cases or social security entitlements.
PERSONAL INJURY CLAIMS
Clients often call in to the office to ask if their personal injury recovery is taxable. Generally speaking, unless there is a specific number allocated as income loss, proceeds from a personal injury settlement are not considered taxable income as they are meant to reimburse the client for noneconominc damages such as pain and suffering.
EMPLOYMENT DISCRIMINATION CLAIMS
One category of recovery which falls into the income bucket is a settlement for wrongful discharge or employment discrimination. This is because a major portion of those claims are specifically seeking lost wages due to the discrimination. However, there is a reduction for attorney fees paid on the amount.
SOCIAL SECURITY BENEFITS
Some people who get Social Security Disability or retirement benefits will have to pay taxes on their benefits. SSI benefits are not taxable. You will be affected only if you have other income in addition to your Social Security benefits. The amount of taxes you might have to pay will vary depending upon whether you file as an individual or jointly with your spouse.
WORKERS’ COMPENSATION BENEFITS
Worker's compensation benefits alone are not taxable. This is because the amount you receive as benefits is already reduced to reflect income taxes having been removed from your paycheck. However, combined SSD and WC benefits may be taxed and you should be aware of this. Even though the WC benefits by themselves are not taxable, they become part of the taxable income when, combined with SSD benefits, they reach a certain threshold which changes periodically as the SSA(Social Security Admininstration) amends them. The SSA should send you an annual report of what you have been paid. If you think the IRS is overtaxing you, you should check it out with your accountant and have it taken care of by your accountant.

HELPFUL LINKS
I have put some helpful links below for your further reading:
- An IRS page: http://www.ssa.gov/planners/taxes.htm
- An article on the National Organization of Social Security Claimants’ Representatives: http://www.nosscr.org/tax.html
- For a short page with tax tips on this subject: http://www.bankrate.com/brm/itax/tips/20010115a.asp
- You can also contact the Taxpayer Advocate Service, an independent entity within the IRS for help: 1-877-777-4778 (toll free), or www.irs.gov/advocate.
Subscribe to:
Posts (Atom)


 Posts

